

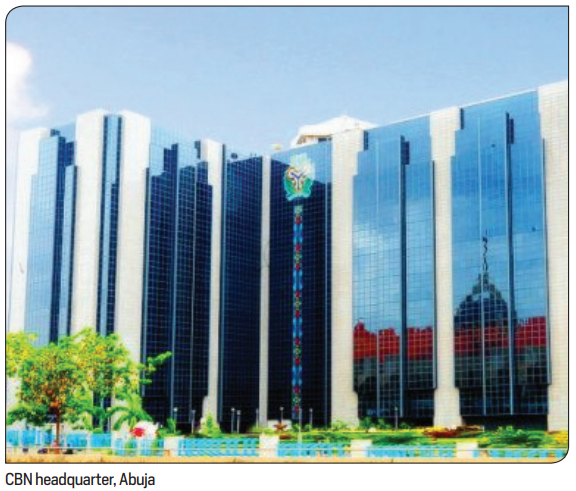
The Federal Government and the Central Bank of Nigeria (CBN) have moved to institutionalise closer coordination of fiscal and monetary policies, with a new framework designed to improve inflation management, government borrowing, liquidity forecasting and private-sector access to credit.
The Federal Ministry of Finance and the CBN sealed a Memorandum of Understanding (MoU) to establish regular consultations, information sharing, joint policy assessments and mechanisms for resolving differences between fiscal and monetary authorities.
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, said the agreement was designed to ensure that coordination between the two institutions would survive changes in government and leadership.
“Today matters not because we are signing a document, but because of what it represents. Our determination to institutionalise coordination between fiscal and monetary policy,” Oyedele said.
He explained that although the Ministry and the CBN have distinct mandates, their policies operate within the same economy and can significantly affect one another.
“Government borrowing affects liquidity and interest rates. Monetary policy affects the government’s financing cost. Tariffs and exchange rates affect prices and revenue. Spending affects demand,” he said.
According to him, the framework will promote the use of common macroeconomic assumptions, more consistent economic forecasts, stronger information sharing and clearer procedures for resolving policy differences.
Oyedele, however, stressed that the arrangement would not undermine the operational independence of the apex bank.
“So this is independence with coordination. The operational independence of the central bank remains sacrosanct. Coordination must never become fiscal dominance,” he said.
He said the CBN would retain responsibility for pursuing price and financial-system stability, while the government would focus on fiscal discipline, accountability and improved cash management.
On inflation, Oyedele said the government’s objective was to bring the rate sustainably into single digits, stressing that the task could not be left to monetary policy alone.
“Inflation is, as a process, a whole-of-government agenda. Our objective is to bring inflation sustainably into single digits and keep it there. And that cannot be monetary policy’s job alone,” he said.
He said fiscal policy would support the objective through disciplined spending, improved cash and liquidity management and more efficient government financing designed to prevent crowding out of private-sector borrowers.
The Minister identified food supply, imported costs, energy and logistics as some of the structural factors driving inflation, saying they required interventions beyond interest-rate adjustments.
He listed measures such as strengthening food reserves, improving access to quality seeds, raising farm yields, expanding irrigation, building climate resilience and improving roads linking farms to markets.
He also urged state governments to remove unnecessary road levies and improve access routes to agricultural communities.
On fuel prices, Oyedele said the government was seeking greater price stability without returning to discretionary fuel subsidies.
He said tax exemptions in the oil sector and improved foreign exchange stability had contributed to moderating prices, warning that policy reversals could put renewed pressure on consumers.
The Minister also stressed the importance of reliable economic data in policymaking, saying outdated or inadequate statistics could undermine economic decisions.
He disclosed that the Ministry was working with the National Bureau of Statistics (NBS) to strengthen data availability, including the Producer Price Index, alongside consumer prices, employment and productivity statistics.
According to him, improved data would enable policymakers to identify inflationary pressures before they are transmitted to consumers.
He added that economic performance should not be measured by GDP growth alone, but also by the number of productive jobs created.
Under the new framework, the Ministry and the CBN will share information on government cash positions, financing plans, credit growth and foreign exchange flows.
“Better coordination starts with a common evidence base,” Oyedele said.
CBN Governor Olayemi Cardoso said the agreement would transform decades of collaboration between the apex bank and the Ministry of Finance into a more formal and structured framework.
Cardoso said the two institutions had historically worked together on inflation, debt sustainability, budget financing, exchange-rate stability, economic reforms and responses to domestic and global shocks.
“What distinguishes today’s event is the formal institutionalisation of that collaboration,” he said.
He said the MoU would cover government cash management, debt issuance planning, liquidity forecasting, macroeconomic analysis and regular policy consultations.
According to him, predictable engagement between the institutions would improve policy decisions, reduce uncertainty and strengthen the country’s capacity to respond to emerging economic challenges.
Cardoso said closer fiscal coordination was particularly important as the CBN moves towards an inflation-targeting framework.
“The success of inflation targeting is known to rest not only on the effectiveness of monetary policy but also on the existence of a supportive fiscal environment,” he said.
He added that the framework would help both institutions align their actions, minimise policy conflicts and pursue shared national economic objectives.
The CBN Deputy Governor, Sani Abdullahi, said closer coordination had become increasingly important because the same external shocks could affect government revenue, foreign exchange inflows, inflation and monetary conditions simultaneously.
He cited disruptions to energy and shipping routes in the Middle East, which could push up oil prices and potentially increase Nigeria’s export earnings, government revenue and foreign exchange inflows, while higher energy, freight and insurance costs could raise domestic prices.
Global inflationary pressures, he added, could also influence interest rates, capital flows and financing conditions.
“This is why coordination matters,” Abdullahi said.
He said implementation of the agreement would require timely and reliable information sharing, joint technical analysis, scenario planning and stress testing.
The framework, he said, would be particularly useful for government cash management, liquidity forecasting, domestic financing operations and assessing changing economic conditions.
Abdullahi also urged the authorities to prepare for different oil-price and production scenarios, noting that the duration of external disruptions and future oil prices could not be predicted with certainty.
He said advance assessment of different oil-price and production outcomes would help the authorities understand their potential impact on government revenue and foreign exchange inflows.
“The value of this agreement will be determined by its implementation. Its success will not be measured by judicial ceremony alone, but by what happens after today,” he said.
Permanent Secretary, Federal Ministry of Finance, Raymond Omachi, said the MoU would provide a transparent framework for aligning fiscal decisions with monetary strategies.
He said a key objective was to strike a balance between inflation control and economic growth, ensuring that government spending did not unnecessarily fuel inflation while monetary tightening did not unduly weaken investment, growth and employment.
Omachi said better coordination of government borrowing and money-market liquidity management would reduce the risk of public-sector financing crowding out credit to private businesses.
The framework, he added, would also address exchange-rate and revenue stability, including foreign exchange management, trade balances and Nigeria’s capacity to absorb economic shocks.
He said regular policy dialogue and data sharing between technical officials of the Ministry and the CBN would now be formally structured.
According to him, the initiative was also expected to create a more predictable investment environment, strengthen public confidence and support a more resilient economy.
Oyedele said the ultimate objective was to prevent fiscal and monetary policies from working at cross-purposes.
“Nigeria has one economy. Fiscal policy cannot succeed without price stability. Monetary policy cannot deliver price stability if fiscal policy pulls in the opposite direction,” he said.
He added that the success of the framework would ultimately be judged by whether future economic management could withstand shocks without depending on the personalities occupying the offices.
“The greatest success will be measured when coordination no longer depends on who holds these offices,” Oyedele said.